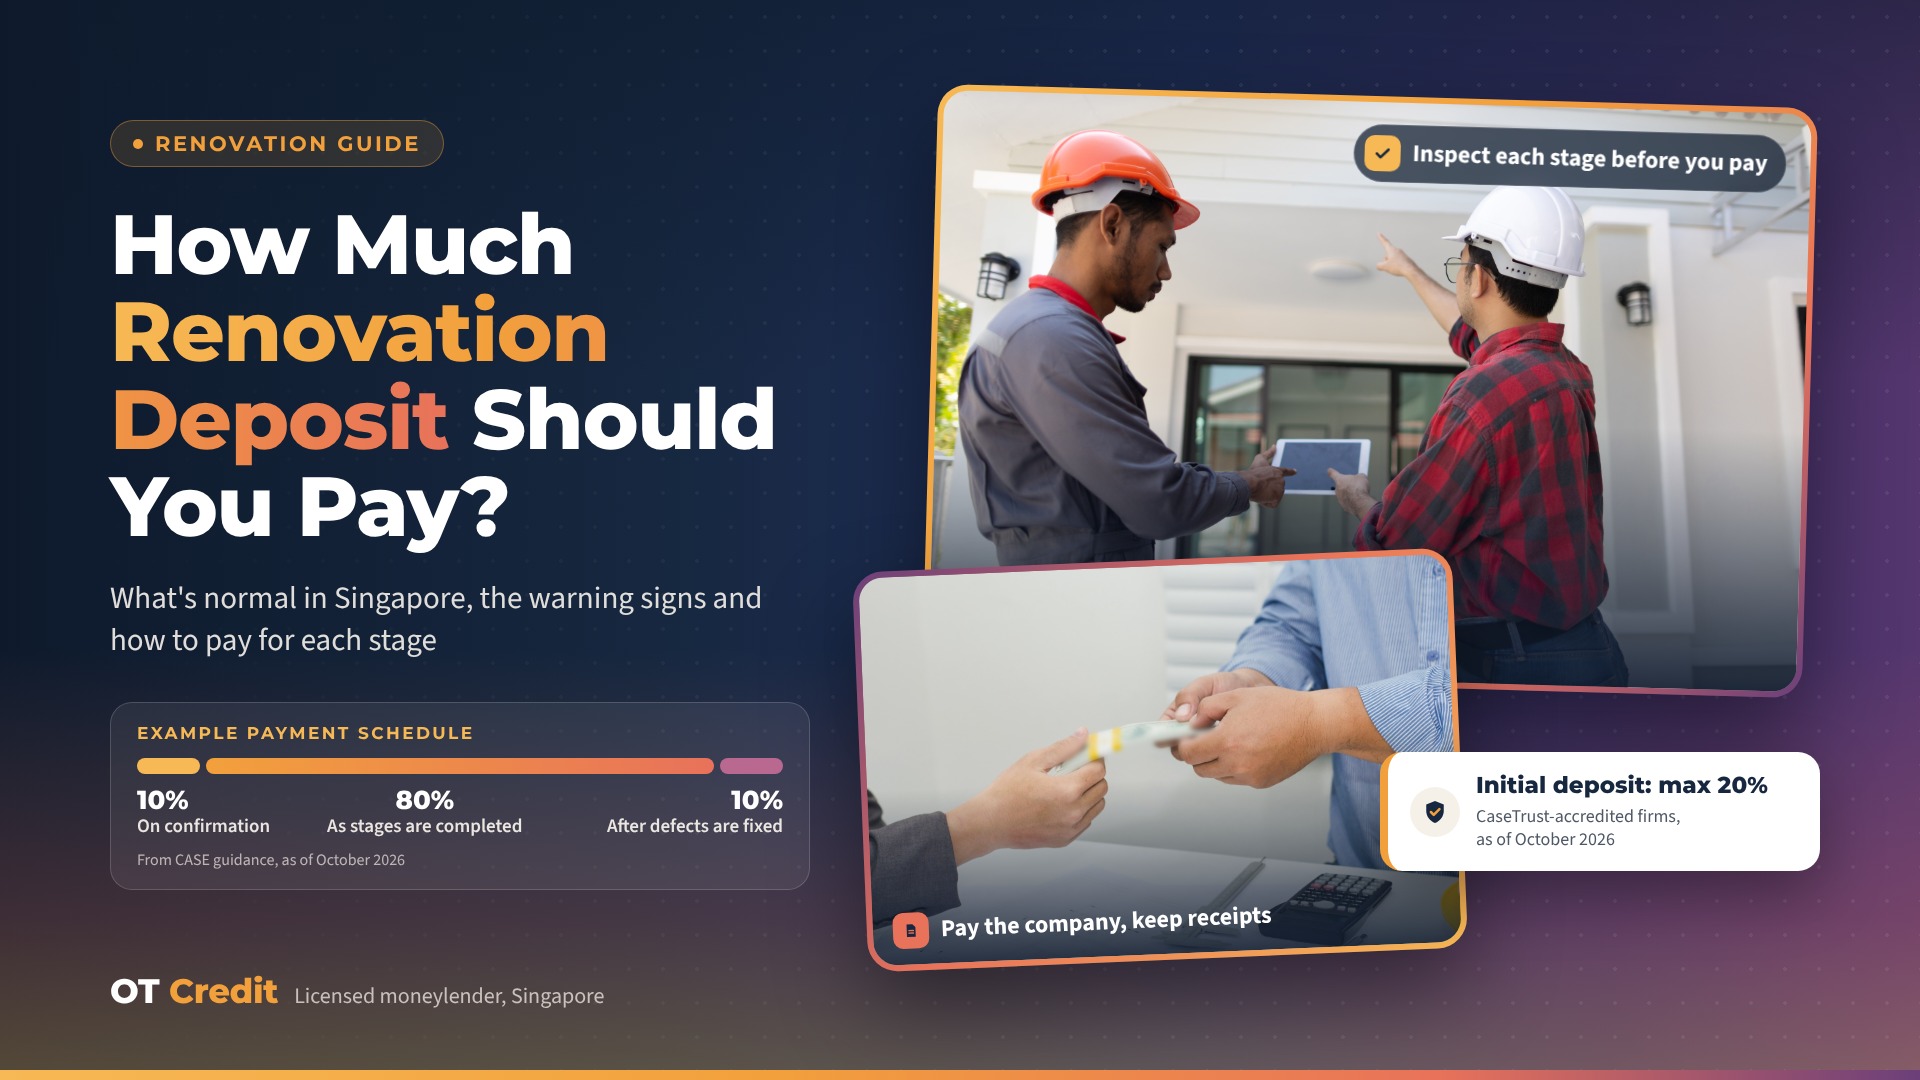
Twenty per cent of the total cost is the most a CaseTrust-accredited renovation firm can ask for as an initial deposit. Ten per cent is what the Consumers Association of Singapore (CASE) puts down at confirmation in its own example payment schedule. Both figures are as of October 2026, and neither is a law that binds every contractor. That’s why the deposit line on a quotation deserves a second read, especially if it says 50%.
Money paid before work starts is the money most exposed if a firm folds. CASE received 787 complaints against renovation contractors in 2025, and consumers reported S$190,667 in renovation prepayment losses that year. Both numbers were lower than in 2024, by 18.2% and 73.8%. Lower isn’t zero, though, and your main defence is control over when each payment leaves your account.
Where the 10% and 20% come from
The 20% ceiling is part of CaseTrust’s renovation accreditation, not a rule for the whole industry. A firm outside the scheme isn’t bound by it, so treat the deposit on its quotation as something to question and, where you can, negotiate. Accredited firms also have to use the CaseTrust Standard Renovation Contract with agreed work and payment schedules, buy a deposit performance bond, nd and protect eligible prepayments. “Are you CaseTrust-accredited?” is a fair first question for any firm.
The 10% is an example, not a rule. CASE’s schedule runs 10% at confirmation, 80% in progressive payments as each stage is completed, and a final 10% once the work is satisfactorily completed and outstanding issues are put right. Your contract sets the real stages.
Put a 50% request next to those numbers, and it’s five times CASE’s confirmation payment and more than double the CaseTrust ceiling. Most of the job would be paid for before you could inspect a single stage of it.
The payment schedule, and the paper behind each payment
However your contract splits the money, tie each payment to a named stage you can check, not a date on the calendar. It also helps to think of every payment as having two pieces of paper: one you should see before the money goes, and one you keep after it’s gone.
The paper trail for each renovation payment (stages from CASE’s example schedule)
| Payment | CASE example | Before you release it | Keep afterwards |
|---|---|---|---|
| On confirmation | 10% | A signed written contract and an itemised quotation, with the company’s own account as the payee. | The signed contract, the quotation and the payment receipt. |
| Progressive payments | 80% in total, as agreed stages are completed. | The stage is finished, and you’ve inspected it; any extra work was agreed in writing first. | A receipt for each payment and every written variation quotation. |
| Final payment | 10% | The work is complete and outstanding defects have been put right. | The final invoice and its receipt. |
Keeping that file isn’t box-ticking. If a dispute ever reaches CASE or the Small Claims Tribunals, it’s what shows what you paid, and for what.
If it’s a BTO flat
No HDB rule decides when a renovation payment schedule starts. That’s down to your contract, whether it ties the first payment to signing, key collection, or some other milestone. HDB regulates the work instead: flat owners must engage an HDB-registered renovation contractor, and works that need approval require a renovation permit before they’re carried out. If your schedule has stage payments falling due before the works can begin, ask the firm to explain why.
When the job grows halfway through
Extra work, usually called a variation order, should change what you owe only with your agreement. The Competition and Consumer Commission of Singapore (CCCS) says in its Guide on Fair Trading Practices for the Renovation Industry that contract revisions and variations should be made only with the consumer’s express agreement. CaseTrust-accredited firms must agree variations in writing before the extra work starts.
In practice, that means a written variation quotation with the added work, the price,e and any change to the timeline. Then slot it into the stage it belongs to, so the schedule still matches the job.
What should make you pause before paying?
A request well above those two figures is the obvious one. Two others matter just as much.
The first is being asked to pay a person rather than the company. The Police have documented a cheating case in which an interior designer persuaded a consumer to transfer payment directly to him instead of to the company’s account, and the promised service wasn’t delivered. One request like that doesn’t prove fraud, but it’s reason enough to stop and contact the company yourself.
The second is thin paperwork: no written contract, or a quotation that squeezes the whole job into a few lines. The CCCS guide supports clear, itemised pricing and detailed descriptions of the work. A quote that can’t tell you what each stage covers can’t tell you when a stage is finished, either.
For an HDB flat, there’s a fourth check. Is the contractor HDB-registered?
What protects the money you’ve already handed over
A contract that ties each payment to an inspected stage does most of the work. CaseTrust accreditation adds a layer: under its prepayment protection, consumers can claim the unused portion of protected prepayments if an accredited business closes. That counts most for the deposit, which is paid before there’s any work to show for it.
The final payment is your other lever. CASE advises making sure outstanding defects are rectified before you pay in full, so agree in writing how defects will be listed and fixed, and what has to happen before that last payment falls due.
The condo deposit and the GST line
Condo owners may be asked for a second deposit, this one by the condo’s management. It’s a separate arrangement, not part of your renovation contract, and its amount, conditions, and refund process vary from one development to another. Ask the management office before work starts, and budget for both.
Then look at how GST appears on the quotation Iff the contractor is GST-registered, its renovation services are generally subject to GST at the standard rate, 9% as of October 2026. IRAS treats a deposit that’s a part-payment as subject to GST when it’s received. A refundable security deposit generally isn’t, unless it’s later applied towards payment.
When the contractor stops turning up
If work stalls or a deposit won’t come back, there are three routes, and each suits a different kind of problem.
CASE can help with renovation disputes, including through mediation. According to a Ministry of Trade and Industry parliamentary reply on 8 May 2024, CASE helped consumers recover money in about half of the renovation prepayment cases it negotiated between 2017 and 2023. That’s encouraging, but it isn’t a promise.
The Small Claims Tribunals hear qualifying disputes over contracts for services, renovation contracts included. A s of October 2026, claims can go up to S$20,000, or S$30,000 if both sides sign a Memorandum of Consent, and eligible claims generally have to be filed within two years.
A police report is for suspected cheating, and you can lodge one online for crimes that don’t need immediate police action. Work that’s late or badly finished is a contract dispute, not automatically a crime.
Paying for it when CPF can’t help
The CPF Board is clear that CPF savings can’t be used for renovation, improvement or repair work. Every stage comes out of cash or borrowed money, so it’s worth deciding where each payment will come from before you sign the contract, not when the invoice lands.
Start with savings if you can. Beyond that, the main routes are a bank renovation loan, card instalment plans or payment platforms, and a personal loan. As one example of a bank renovation loan, DBS publishes a limit of up to six times monthly income or S$30,000, whichever is lower, subject to eligibility and approval (as of October 2026), and may issue the money as cashier’s orders in the contractor’s name. Other banks set their own terms, and our renovation loan guide goes through how these loans work. Card and payment-platform fees depend on the provider, so check its current fee schedule. Costs and eligibility differ across all of these, so compare the total cost before you choose.
A personal loan from a licensed moneylender fits one narrow situation: a stage is finished and inspected, the payment’s due, and your savings or bank loan isn’t ready yet. It’s a poor fit for an oversized deposit. If you’re already paying an HDB loan, remember that instalment is part of the picture too: any approval depends on how the lender assesses your income, existing loans and repayment ability.
If you borrow, keep the lender’s paperwork as carefully as the contractor’s
Everything above about contracts and receipts applies to a loan as well, and the Registry of Moneylenders spells out what you should receive.
Before you commit, a licensed moneylender has to take you through the loan’s terms in a language you understand and give you a copy of the contract, known as the Note of Contract. Read it the way you’d read the renovation quotatio. Thee Registry singles out the repayment schedule, the interest rate,e and the fees as the terms to understand, and once the loan is granted, it tells borrowers to check that the principal amount is correct.
After that, two kinds of paper should keep arriving: a receipt every time you make a repayment, and a statement of account for each loan at least once every January and July. The Registry’s advice is to check both for the name, amount,nt and date, and to keep every receipt and statement as evidence of what you’ve paid. It’s the same habit as keeping a receipt for each renovation stage, just running in the other direction.
The Registry lists granting a loan without a copy of the Note of Contract, or without properly explaining its terms, among the practices that aren’t acceptable, and it asks borrowers to report them. You can reach the Registry on 1800-2255-529.
The paperwork also makes one thing plain: the loan is a separate agreement from the renovation. The Registry states that you’re legally obliged to fulfil any loan contract you enter into with a licensed moneylender, so a contractor who walks off the job doesn’t automatically cancel your repayments. If they start to feel heavy, talk to the lender early. The Registry’s borrower guide also lists organisations that help with debt, Credit Counselling Singapore among them.
We’ve kept borrowing limits and fee caps out of this article, because they’re the same whatever the loan is for. You’ll find t along hem, with how to check a lender’s licence, in our guide to what licensed moneylenders can and can’t do in Singapore.
If you do borrow for a renovation, match the loan to work that’s already done and inspected, never to an oversized deposit, and work out the total cost rather than just the monthly instalment. T Therenovation runs on the contractor’s schedule. Your repayments run on the loan agreement.
Before you deal with any lender, do what you’d do with a contractor and check the official register. For moneylenders, that’s the Ministry of Law’s list of licensed moneylenders.
Bring the quotation with you.
If a stage is done and the payment’s due before your other funds are, bring your renovation quotation along to our Jurong East office. W e’ll go through the loan’s terms with you line by line, including the repayment dates on the Note of Contract, before you decide anything. Whether we can lend, and how much, depends on our assessment of your income, existing loans, and repayment ability.
OT CREDIT PTE. LTD.<br> Licensed by the Ministry of Law’s Registrar of Moneylenders (Licence No. 101/2026)<br> 135, JURONG GATEWAY ROAD, #01-323, SINGAPORE 600135<br> 62920119
Related reading
- What Licensed Moneylenders Can & Can’t Do in Singapore
- Renovation Loan Singapore: The Complete Guide to Rates, Eligibility & How to Apply
Sources
- Registry of Moneylenders, Ministry of Law: FAQs on Borrowing From Licensed Moneylenders
- Registry of Moneylenders: List of Licensed Moneylenders in Singapore
- CPF Board: Can I use my CPF savings for renovation and repairs of my property?
- Ministry of Trade and Industry: Written reply to PQs on disputes arising from interior design and renovation firms, 8 May 2024
- Singapore Courts: How to file and serve a small claim
- Consumers Association of Singapore (CASE): CaseTrust renovation accreditation; renovation consumer guidance; media release on 2025 complaints (February 2026)
- Competition and Consumer Commission of Singapore: Guide on Fair Trading Practices for the Renovation Industry
- Housing and Development (Renovation Control) Rules, Singapore Statutes Online
- Inland Revenue Authority of Singapore (IRAS): GST guidance on deposits
- Singapore Police Force: online police reports
- DBS: Renovation Loan product information