Singapore’s New Mandatory Cooling-Off Period for Licensed Moneylender Loans
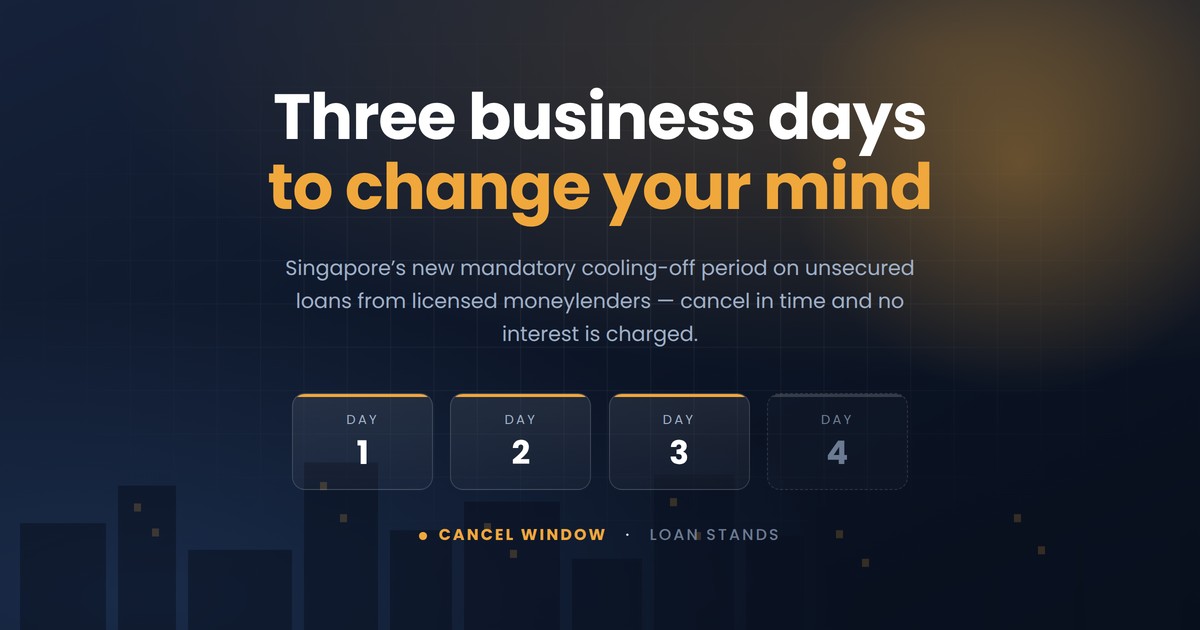
Singapore’s new mandatory cooling-off period lets you cancel an unsecured loan from a licensed moneylender within three business days — and caps what the lender is allowed to keep if you do. Here is what it covers, what cancelling actually costs, and where the rule stops.
The short version
- Three business days to cancel on unsecured loans from licensed moneylenders. Business loans are excluded.
- Saturdays, Sundays and Singapore public holidays do not count towards the three days.
- Cancel in time, and no interest is charged at all.
- The lender may keep only a capped slice of the loan approval fee: up to $50 on loans of $5,000 or less, up to 3.5% of the principal on anything larger — and never more than the fee it actually charged you.
- Whatever happens, you cannot end up repaying more than the principal amount of the loan.
- In force from 15 September 2026. The Ministry of Law announced it on 31 August 2026.
What changed today
Signing a loan agreement in Singapore used to be close to a one-way door. Change your mind the next morning and the moneylender was entitled to hold on to the entire loan approval fee, plus any interest that had already accrued — so a decision made under pressure on Monday was still costing you on Tuesday.
From today, that door swings both ways. The Ministry of Law (“MinLaw”) has made a cooling-off period of three business days compulsory on every unsecured loan taken from a licensed moneylender, with one carve-out: business loans. Inside that window, you may cancel the loan and hand the money back at a sharply reduced cost.
“Three business days” is counted the way you would hope. Saturdays, Sundays and Singapore public holidays are left out, so a loan signed on a Thursday still leaves you with Friday, Monday and Tuesday to reconsider — a genuine long weekend to think, not a technicality that expires before the working week restarts.
What cancelling costs you
The cooling-off period is not a free trial, and it was never designed to be. A lender still does real work to approve a loan — identity checks, income verification, the credit assessment — and the rule lets it recover a capped part of that cost through the loan approval fee it charged you.
| Principal of the unsecured loan (non-business) | Most the lender may retain if you cancel |
|---|---|
| $5,000 or less | $50, and never more than the loan approval fee charged |
| More than $5,000 | 3.5% of the loan principal, and never more than the loan approval fee charged |
Two things about that table are worth slowing down for.
First, both figures are ceilings, not prices. If the approval fee you were charged was smaller than the cap, the smaller number is what the lender keeps.
Second, the loan approval fee in Singapore is already capped at 10% of the principal under the moneylending rules — which means the 3.5% ceiling genuinely bites on larger loans, cutting the cost of a change of mind to roughly a third of what the fee would otherwise have been.
The arithmetic of a cancellation is simple enough to do on the back of a receipt. You repay the cash that actually reached you — the principal minus the approval fee that was deducted upfront — plus the capped portion of that fee the lender is allowed to keep. No interest is charged for the days you held the money, and the total you hand back can never exceed the principal amount of the loan.
Two worked examples
A $1,000 loan. With a 10% approval fee, $100 is deducted upfront, and $900 reaches your hands. Cancel inside the cooling-off window, and you repay $950: the $900 you received, plus the $50 the lender may retain. Changing your mind costs you $50, not $100 and not a month of interest.
A $10,000 loan. The same 10% fee means $1,000 deducted and $9,000 disbursed. Because the principal is above $5,000, the cap is 3.5% of $10,000, or $350. You repay $9,350 — the $9,000 you received plus $350 — and the lender returns the remaining $650 of the fee it had collected. (This second illustration is our own working of the rule, not an example published by MinLaw.)
Where the rule stops
- Business loans are out. The cooling-off period applies to unsecured personal borrowing; loans taken to fund a business fall outside it.
- Licensed lenders only. The rule is part of the framework governing licensed moneylenders. An unlicensed operator — a loan shark, whatever the advertisement calls itself — offers no cooling-off period, no fee cap, and no recourse, because it is breaking the law before you even sign.
- It is a right to cancel, not a right to keep the cash. Cancelling means returning the money that was disbursed to you, in full, within the window.
Why MinLaw brought it in
MinLaw built the framework in consultation with the Credit Association of Singapore, the professional association representing licensed moneylenders, and the balance it was aiming for is stated plainly: give borrowers room to reconsider credit decisions that are sometimes made on impulse, while making sure lenders are still compensated for the work of granting a loan.
The start date was not accidental either. MinLaw set commencement at 15 September 2026 to give licensed moneylenders time to adjust their processes and systems, with the Registry of Moneylenders working alongside the industry on implementation.
The other change most borrowers missed
Earlier this year, in April 2026, the Registry also updated its Professional Service Handbook for licensed moneylenders with three practices it encourages the industry to adopt:
- Rewards for paying well — discounts or rebates on interest and fees for borrowers who repay on time or settle ahead of schedule.
- Digital touchpoints — tools such as an online portal where you can watch your own loan servicing rather than phoning to ask.
- Real help for borrowers in difficulty — restructuring a repayment schedule to something a struggling borrower can actually meet, or referring them to a Social Service Agency.
These are encouraged best practices rather than legal obligations, which makes them a fair question to put to any lender before you borrow: do you do these things?
How to be sure you are at a licensed lender
The cooling-off period only protects you if the lender is licensed, so check before anything is signed. Licensed moneylenders are listed on the Registry of Moneylenders on MinLaw’s website. They do not tout for business through text messages, phone calls or social media — an unsolicited loan offer in your inbox is a reliable sign of an illegal operator. And a licensed lender must meet you in person at its approved place of business to verify your identity face to face before granting a loan.
Borrowing with OT Credit
At our Jurong East office, nothing about this changes how we work — it simply writes into law what a careful loan conversation should already look like. We will tell you what the loan costs before you sign, when your three business days end, and exactly what you would repay if you decided to walk away. If that conversation makes you want to wait, wait.
Frequently asked questions
When does the cooling-off period start?
It takes effect on 15 September 2026. MinLaw announced the change on 31 August 2026.
How long is three business days, really?
Three days that are not Saturdays, Sundays, or Singapore public holidays. A loan signed on Thursday runs through Friday, Monday and Tuesday where no public holiday intervenes. Ask your lender to confirm the exact cut-off in writing.
Does it apply to business loans?
No. Business loans are specifically excluded. The cooling-off period covers unsecured loans other than business loans.
What exactly do I repay if I cancel?
The money that was disbursed to you — the principal after the approval fee was taken upfront — plus the capped portion of that fee the lender may retain: $50 for loans of $5,000 or less, or 3.5% of the principal above that, and in neither case more than the fee you were charged.
Will I be charged interest for the days I had the money?
No. Cancel within the window, and no interest is charged.
Could I end up owing more than I borrowed?
No. The total repayable when you cancel within the cooling-off period cannot exceed the principal amount of the loan.
I signed my loan before 15 September 2026. Am I covered?
The requirement takes effect on 15 September 2026, so a loan granted before that date is not covered by it. If you are close to the line, ask your lender directly what applies to your agreement.
Does cancelling hurt my chances of borrowing later?
Cancelling inside the window is a right the law now gives you, and MinLaw’s announcement attaches no penalty to using it. If you are worried about how a lender will view it, ask before you sign rather than after.
What if a lender refuses to honour the cooling-off period?
Licensed moneylenders are regulated by the Registry of Moneylenders under MinLaw, and complaints about a licensed lender’s conduct go there. If the lender is not on the Registry’s list, you are dealing with an illegal operator and should report it to the police.
Does this apply to loans from banks?
No. This rule sits within the framework for licensed moneylenders. Bank lending is regulated separately.
Source: Ministry of Law, “Mandatory Cooling-off Period for Loans Taken from Licensed Moneylenders”, 31 August 2026 (mlaw.gov.sg). This article is general information about a regulatory change, not financial or legal advice. For the terms that apply to your own loan, speak to us before you sign.